
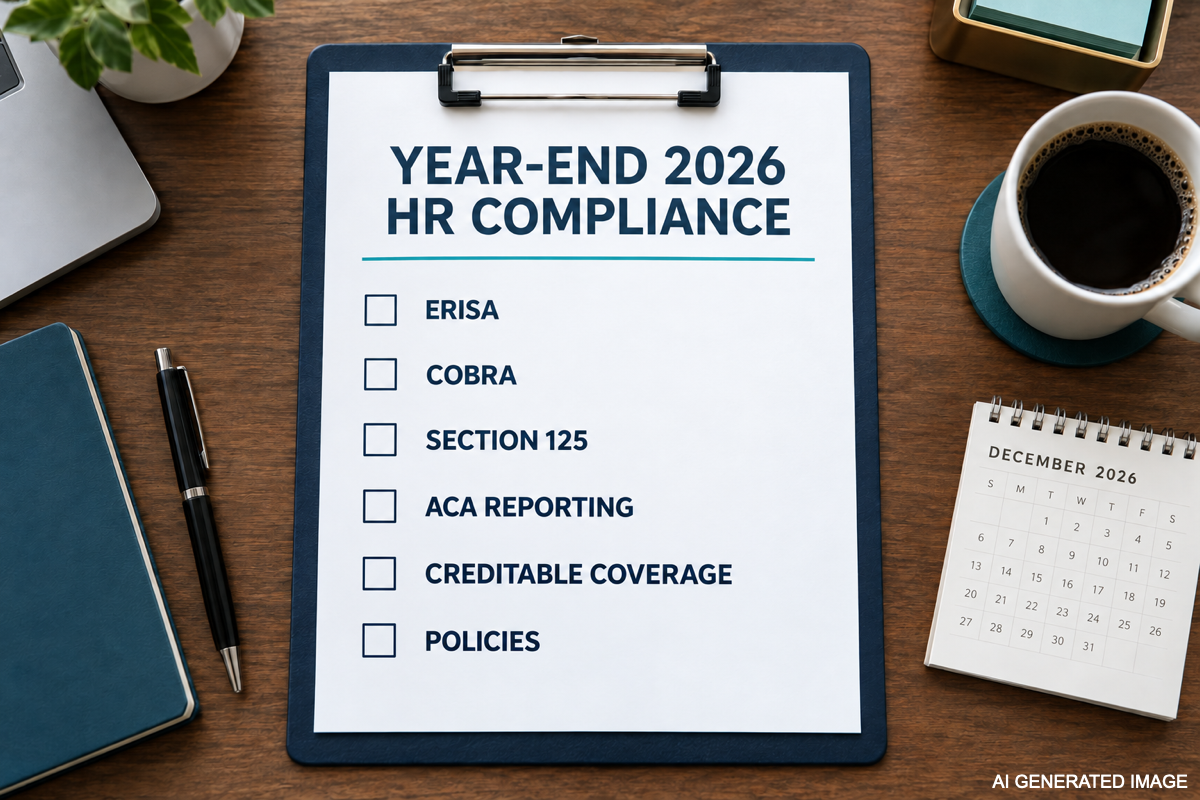
Essential HR compliance checklist for year-end 2026. Covers ERISA, COBRA, Section 125, ACA reporting, creditable coverage notices, and policy updates.
Breast Cancer Awareness Month is a reminder to know your normal, discuss screening with your doctor, and understand how your health coverage supports cancer care.
Learn how environmental factors affect employee vision, what you can do to improve your workplace, and why vision insurance matters for retention and morale.
Online calculators are only a starting point. Here is a simple four-part way to think through how much life insurance fits your family and your budget.
Most employees don't understand their benefits, and it's costing employers money. Learn practical ways to improve health care literacy at your organization.
A landmark study found that people eating ultra-processed foods consumed more calories and gained weight. Learn why and how to make healthier choices.
The PCORI fee is due July 31 on IRS Form 720. Find out which employers owe it, the 2026 rate, how to calculate covered lives, and how to file on time
Learn simple Fourth of July safety tips to help prevent injuries, fires, and accidents while enjoying fireworks and holiday celebrations.
As the summer sun beckons and thirst levels rise, it's tempting to reach for a cold, fizzy beverage. But before you pop open that soda can, consider this: your drink choice has long-term implications for your health. The Hidden Risks in Your Glass A comprehensive study by the International Agency for Research on Cancer (IARC) analyzed data from over 451,000 individuals across 10 European countries over a 16-year period. The findings revealed that consuming two or more 250 ml glasses of soft drinks daily—whether sugar-sweetened or artificially sweetened—was associated with a higher risk of all-cause mortality compared to those who drank less than one glass per month. Delving deeper: Artificially Sweetened Beverages : Individuals consuming two or more glasses daily had a 26% higher risk of death compared to those who consumed less than one glass per month. Specifically, there was a 52% increased risk of death from circulatory diseases. Sugar-Sweetened Beverages : Those consuming one or more glasses daily faced a 59% higher risk of death from digestive diseases. All Soft Drinks : A notable association was found between soft drink consumption and increased mortality from Parkinson's disease. Alternatives That Aren’t Any Healthier Think fruit juice or energy drinks are a safer bet? A study involving 13,440 U.S. adults aged 45 and older found that each additional 12-ounce serving of sugary beverages, including 100% fruit juice, was linked to an 11% higher risk of all-cause mortality. Specifically, each additional 12-ounce serving of fruit juice was associated with a 24% increased risk. Watch the sugar content of iced coffee beverages and alcoholic cocktails as well. Lifestyle Factors Matter, Too It's essential to note that high soft drink consumption often correlates with other unhealthy lifestyle choices. The IARC study observed that individuals who drank more soft drinks typically had higher body mass indexes and were more likely to smoke. Even after adjusting for factors like diet, physical activity, smoking, and education, the association between soft drink consumption and increased mortality risk remained significant. Refreshing Alternatives for the Season Looking to quench your thirst without compromising your health? Here are some delightful, healthier options: Infused Water : Add slices of citrus fruits, cucumbers, or berries to your water for a refreshing twist. Herbal Iced Teas : Brew teas like hibiscus or mint, chill them, and enjoy over ice. Sparkling Water with a Splash : Mix sparkling water with a splash of 100% fruit juice for a fizzy treat. Homemade Lemonade : Use fresh lemons, water, and a touch of natural sweetener like honey or stevia. Coconut Water : A natural source of electrolytes, perfect for rehydration. Final Thoughts Summer is a time for relaxation and enjoyment. By making informed beverage choices, you can savor the season while prioritizing your health. So, the next time you're reaching for a drink to beat the heat, consider these healthier alternatives. Your body will thank you!
Whether you’re planning a weekend getaway or a long-awaited international adventure, setting off on a trip is always exciting—but can also be unpredictable. That’s why preparing for the unexpected, especially when it comes to your health, is essential. Knowing what your medical coverage includes (and doesn’t) while traveling can help you stay healthy, avoid costly surprises, and soak up the unforgettable moments on your journey. Let’s walk through some proactive steps you can take before packing your bags—from vaccinations and insurance to emergency planning and fraud protection. 1. Know What Your Health Plan Covers—And Where Medical surprises aren’t on anyone’s itinerary—but it’s best to be prepared. Start by knowing how your insurance policy covers (or doesn’t) the region you’re traveling to. Individual health policyholders, review your insurer’s network coverage. Some plans only cover in-network or state-specific services, while others offer broader emergency coverage or travel-specific riders. Consult your insurance agent to get help reviewing your policy. Medicare beneficiaries, Original Medicare (Parts A & B) typically doesn’t cover medical care outside the U.S., except in limited circumstances. If you have a Medicare Advantage Plan, it may include emergency and urgent coverage abroad, but this varies by provider. Check your plan’s Evidence of Coverage or speak to your plan representative before traveling. 2. Consider Supplemental Insurance If you're a frequent traveler or heading abroad, look into some options to help cover you. Some options include: Travel Medical Insurance : Plans offer emergency coverage during trips outside the U.S. and tend to be affordable. Evacuation Insurance : This covers transport to a qualified medical facility if the nearest care is inadequate. An evacuation clause is often, but not always, included in a travel insurance plan. Medicare Supplement Insurance (Medigap) : Some Medigap policies cover emergency care abroad, typically up to plan limits and with a deductible. Critical Illness Insurance : A lump-sum payout can provide financial flexibility in case you’re diagnosed with a covered condition like a heart attack or stroke during travel. Be sure to read the fine print—some policies require you to be under a certain age, and preexisting conditions may not be covered. Your licensed insurance agent can help talk you through your options. 3. Keep Your Medical Info Handy Consider using a secure health app or digital wallet to access all your health records quickly. But just in case your phone is inaccessible, bring physical copies of these important documents as well: Your insurance or Medicare cards Emergency contact numbers (include the country code +1 if you’re traveling abroad) A medication list with dosages Allergy and medical condition alerts Pack all essential paperwork together in a waterproof sleeve in your luggage, and leave a second copy with someone back home. 4. Schedule Preventive Care Before Departure Most insurance plans cover preventive care services like wellness visits, vaccinations, and screenings. Before your trip, check these tasks off your list: Get vaccinated : Make sure you’re up to date on your flu, COVID-19, and tetanus shots. If traveling internationally, check the CDC recommendations for the region you’re visiting, which may include Hepatitis A/B, typhoid, or yellow fever vaccinations.